Mortgage Rate Update — November 2026 | What South Shore, Boston & Cape Cod Buyers & Sellers Need to Know
Charles King
Charles King is a top-producing real estate agent in Hingham, MA and a trusted Realtor serving the South Shore of Massachusetts, including Hanover, Hu...
Charles King is a top-producing real estate agent in Hingham, MA and a trusted Realtor serving the South Shore of Massachusetts, including Hanover, Hu...
Mortgage Rate Update — November 2026 | What South Shore, Boston & Cape Cod Buyers & Sellers Need to Know
Published: November 19, 2026
By: Charles King, Charles King Group | Hingham, MA
Sources: Mortgage Bankers Association (MBA) weekly applications survey, as reported by CNBC, November 2026; Mortgage News Daily, November 2026; local context from Charles King Group agent observations, November 2026
Mortgage rates had been easing for about a month. Last week that stopped. The average 30-year fixed rate jumped to 7.35%, its highest level in three weeks, and mortgage applications fell across the board. For buyers and sellers in Hingham, Cohasset, Scituate, Norwell, and Hanover, as well as in Boston and on Cape Cod, the change shows up in monthly payments and in how many buyers are out shopping. Here’s what happened, why, and what it means for your next move.
What Happened to Mortgage Rates This Week?
According to the Mortgage Bankers Association’s weekly survey, the average contract rate on a 30-year fixed mortgage with a conforming loan balance ($832,750 or less) rose to 7.35% from 7.21%. Points rose to 0.79 from 0.75, including the origination fee, for loans with a 20% down payment.
That’s a jump of 14 basis points. A basis point is one-hundredth of a percentage point, so 14 basis points means the rate went up 0.14 percentage points in a single week. Points are upfront fees paid at closing, with one point equal to 1% of the loan amount.
Total mortgage application volume fell 2.3% from the week before, on the MBA’s seasonally adjusted index.
What it means: The rate relief buyers saw over the past month has partly reversed. Anyone who was waiting for rates to keep falling just watched them go the other way.
Why Did Mortgage Rates Jump This Week?
Mortgage rates follow the bond market, especially Treasury yields. Those yields rose last week after new data showed inflation accelerated in October, and after Federal Reserve officials said more rate hikes may be needed in the coming months.
“Treasury yields rose last week amid data showing inflation accelerated in October and Fed officials acknowledging that additional rate hikes may be needed in the coming months,” said Joel Kan, vice president and deputy chief economist at the MBA.
What it means: Rates are moving on inflation news, not on anything specific to housing. Until inflation cools, expect rates to stay volatile from week to week.
How Much Does a Rate Increase Add to a Monthly Payment?
Here’s an illustrative example. On a $700,000 loan (under the conforming limit), a 30-year fixed payment for principal and interest only works out to roughly: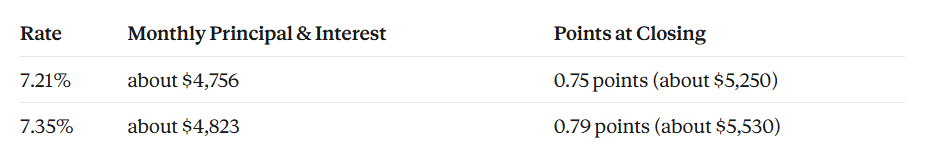
That’s roughly $67 more per month, or about $800 a year, plus about $280 more in upfront points. Taxes, insurance, and any condo fees come on top of that. Figures are illustrative and should be verified with a lender.
What it means: One week’s rate move won’t make or break most purchases, but it adds up. Buyers who are close to their budget limit feel it first.
Are Buyers Still Applying for Mortgages?
Fewer are. Applications for a mortgage to buy a home fell 3% for the week and were 18% below the same week a year ago. The MBA points to two pressures: affordability, and weaker confidence in the economy because of persistent inflation.
What it means: Fewer buyers are actively shopping. For buyers who are ready, that means less competition. For sellers, it means pricing and presentation matter more than they did a year ago.
Is Anyone Still Refinancing?
Very few. Refinance applications fell 2% for the week and were 54% lower than a year ago. The exception was FHA loans. Federal Housing Administration refinances rose almost 7%, because the FHA rate was about 30 basis points (0.30 percentage points) below the conforming rate. FHA loans allow low down payments at lower rates but require mortgage insurance.
What it means: Most homeowners with loans from recent years have no reason to refinance at 7%+. If you have an FHA loan or qualify for one, it’s worth asking a lender whether the lower FHA rate changes your numbers.
How Do Higher Rates Affect South Shore, Boston and Cape Cod Buyers?
National averages don’t land evenly. Here’s how this plays out in the markets we serve:
South Shore (Hingham, Cohasset, Scituate, Norwell, Hanover). The MBA’s 7.35% figure applies to conforming loans of $832,750 or less. In Hingham and Cohasset, many single-family purchases need a loan above that amount, which means high-balance or jumbo financing that lenders price separately. Buyers in those towns should get a quote for their actual loan size rather than relying on the headline rate. In Scituate, Norwell, and Hanover, more purchases fall within conforming or high-balance limits, so the national rate move translates more directly into payments. [Agent observation; verify]
Boston (Back Bay, South End, Beacon Hill, Charlestown, South Boston/Seaport). Condo buyers carry the mortgage plus monthly condo fees, so a rate increase squeezes the total payment harder. Units with high fees or no parking feel it first.
Cape Cod (Barnstable, Chatham, Falmouth, Sandwich, Harwich). A meaningful share of second-home buyers pay cash or draw on equity, which softens the rate impact at the higher end. Year-round buyers who finance are just as rate-sensitive as anywhere else, and late fall is already the Cape’s slowest season. [Agent observation; verify]
Metro West, Northern Middlesex & the Merrimack Valley, and Bristol County. The same split applies. Higher-priced towns like Wellesley and Weston lean on jumbo financing, while more affordable markets such as Lowell, Taunton, and Attleboro are where FHA and conforming rates matter most.
What it means: Your loan size and loan type decide how much this rate move affects you. Get a quote based on your actual purchase price, not the national average.
What This Means for Buyers
- Get pre-approved at today’s rate. Know your payment at 7.35%, not at last month’s lower number.
- Ask about a rate lock. With rates moving week to week, locking once you’re under agreement protects your budget.
- Compare loan types. If you qualify, an FHA loan’s lower rate may offset the cost of mortgage insurance. In Hingham and Cohasset, compare jumbo quotes from more than one lender.
- Negotiate for credits. With purchase applications down 18% from a year ago, sellers are more open to credits toward a rate buydown, which lowers your monthly payment.
- Buy what works at today’s rate. Refinancing later is possible, but don’t count on it.
What This Means for Sellers in Hingham, Cohasset, Scituate, Norwell & Hanover
- Price for the buyers who are actually out there. Fewer buyers are applying for mortgages, so overpriced homes will sit longer.
- Think in monthly payments. Buyers shop by payment. A seller-paid rate buydown can do more for a buyer than a small price cut, and it can protect your sale price.
- Know your buyer’s financing. In higher-priced Hingham and Cohasset listings, jumbo-financed and cash buyers dominate. In Scituate, Norwell, and Hanover, conforming and FHA buyers are a larger share of the pool.
- Prepare before you list. When buyers have fewer dollars to stretch, a clean, well-presented home with inspection issues handled stands out.
November 2026 Outlook
Mortgage rates have stayed essentially flat to start this week, according to Mortgage News Daily. More housing data is due soon: the Census report on housing starts and building permits, and the National Association of Realtors’ pending home sales index. Both will show whether the slowdown in buyer activity is deepening. If you’re weighing a purchase or sale on the South Shore, in Boston, or on the Cape, let’s run the numbers for your town and your loan size together.
Wondering what today’s rates mean for your budget or your sale?
Whether you’re buying on the South Shore, in Boston, or on the Cape, I can help you see what your payment looks like at your price point, and which homes have room to negotiate.
Frequently Asked Questions
What are mortgage rates right now in November 2026?
The average 30-year fixed rate for conforming loans of $832,750 or less rose to 7.35% from 7.21% in the Mortgage Bankers Association’s latest weekly survey, the highest level in three weeks. Points rose to 0.79 from 0.75 for loans with 20% down. Rates were essentially flat to start the following week. Source: Mortgage Bankers Association via CNBC and Mortgage News Daily, November 2026.
Why did mortgage rates go up in November 2026?
Treasury yields rose after data showed inflation accelerated in October and Federal Reserve officials said more rate hikes may be needed in the coming months. Mortgage rates tend to follow Treasury yields, so they rose too. Source: Mortgage Bankers Association via CNBC, November 2026.
How much does a higher mortgage rate add to a monthly payment in Scituate, Norwell or Hanover?
On an illustrative $700,000 loan, moving from 7.21% to 7.35% raises the 30-year principal and interest payment from about $4,756 to about $4,823, roughly $67 more per month. Taxes and insurance are extra. Source: Mortgage Bankers Association rates via CNBC, November 2026; illustrative calculation, verify with a lender.
Do higher mortgage rates affect buyers in Hingham and Cohasset differently?
Often, yes. The 7.35% average applies to conforming loans of $832,750 or less, and many Hingham and Cohasset single-family purchases require larger high-balance or jumbo loans that lenders price separately. Buyers in those towns should get a quote for their actual loan size. Sources: Mortgage Bankers Association via CNBC, November 2026; Charles King Group agent observations, November 2026.
Should Boston condo buyers wait for mortgage rates to drop?
Waiting has risks of its own, because rates rose 0.14 percentage points in a single week after a month of declines. Boston condo buyers should budget for the full monthly cost, including condo fees, at today’s rate, and buy only if that payment works. Sources: Mortgage Bankers Association via CNBC, November 2026; Charles King Group agent observations, November 2026.
Is refinancing worth it right now in Massachusetts?
For most homeowners, not at current rates. Refinance applications were 54% lower than a year ago, though FHA refinances rose almost 7% because the FHA rate was about 0.30 percentage points below the conforming rate. Homeowners with FHA loans should ask a lender to run their numbers. Source: Mortgage Bankers Association via CNBC, November 2026.
Is it a good time to buy a home on the South Shore or Cape Cod with rates above 7%?
For buyers who are financially ready, there is less competition. Mortgage applications to buy a home were 18% below a year ago, which gives prepared buyers more room to negotiate credits and terms. The right time still depends on whether the payment works at today’s rate. Sources: Mortgage Bankers Association via CNBC, November 2026; Charles King Group agent observations, November 2026.